
On this page
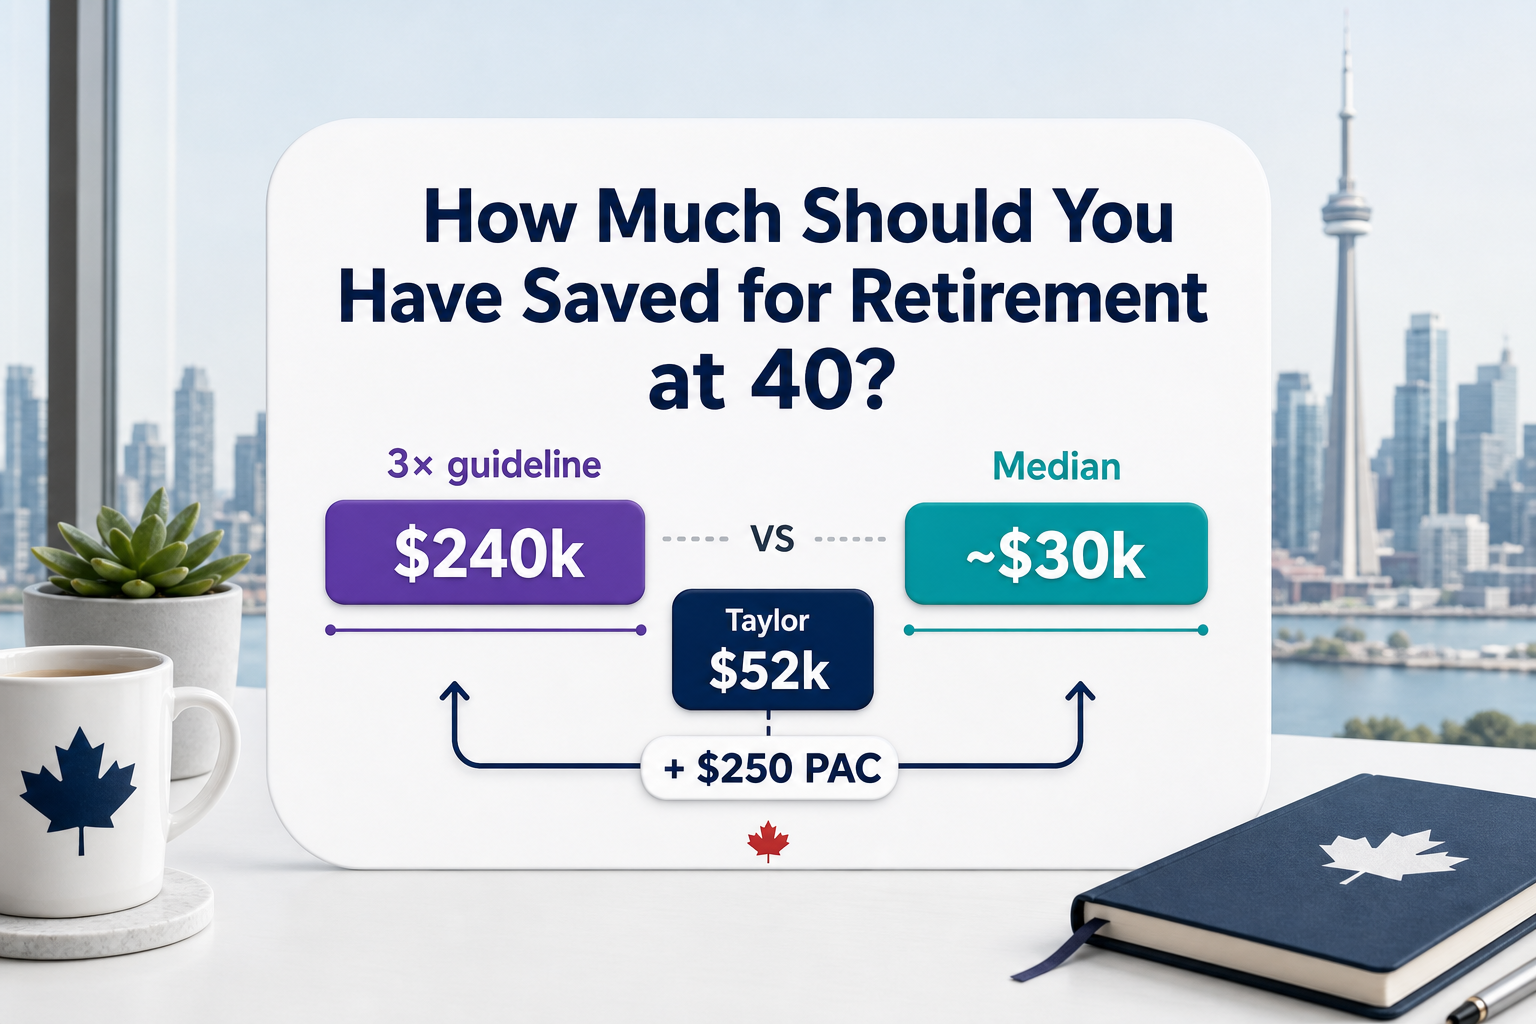
There is no single “correct” balance at 40. Two useful Canadian frames: a Fidelity-style ~3× salary guideline — aspirational, US-rooted, not law — and StatsCan median reality for the 35–44 band — what a typical registered retirement pot looks like. Neither is “your number.”
The decade job is habit + runway, not panic-comparing to a US retirement-multiple table. This page is not a catch-up-at-50 playbook, not a last-mile-at-60 checklist, and not a nest-egg formula.
The 3× guideline (not a grade)
Fidelity-style milestones commonly cited online run roughly ~1× by 30, ~3× by 40, ~6× by 50, ~8× by 60, and ~10× by the late 60s. Fidelity Canada’s age-40 content uses the three-times-salary checkpoint; the fuller ladder is US-rooted and often assumes something like a 15% savings rate, long equity exposure, retirement near 67, and a US Social Security context.
Canada’s CPP and OAS are a future floor — so the same lifestyle may need a lower personal multiple than a US table implies. Treat 3× as a guideline / goalpost, not a pass/fail grade and not Canadian law.
Canadian median reality
For ages 35–44 (major income earner), widely cited Survey of Financial Security aggregations put RRSP/RRIF/LIRA median around $30,000 and mean around $82,100. Prefer the median. The mean is pulled up by high balances — roughly 2.7× the median in those cited tables. Those dollar bands are secondary aggregations of StatsCan SFS (commonly referenced to the 2019 age-band consumer table); do not invent provincial medians.
A household between the median band and a 3× multiple is normal, not a failure. The useful question: is the contribution habit locked, and is the runway still long enough to compound?
Dual view on an $80,000 salary
| Frame | Amount | Label |
|---|---|---|
| Gross salary (illus.) | $80,000 | Illustration |
| Fidelity-style 3× guideline | $240,000 | Guideline, not law |
| SFS median RRSP/RRIF/LIRA, ages 35–44 | ~$30,000 | Prefer median; secondary aggregation |
| SFS mean (same band) | ~$82,100 | Skewed — not “typical” |
3 × $80,000 = $240,000. On $75,000 salary, 3× = $225,000.
Decade spine: habit and runway
From about 40 to a retirement age often cited near 65, you still have ~20–25 years of compounding left (unless you retire earlier). Own this decade’s job:
- Lock automatic contributions (a PAC).
- Raise the savings rate when income rises.
- Use registered room without treating room formulas as this page’s job — Contribution Limits Cheat Sheet and TFSA Contribution Room 2026 own the limits (2026 TFSA dollar limit is $7,000 on canada.ca).
- Keep lifestyle inflation from eating raises.
Kids and a mortgage often compete for cash — one line, then stop. Catch-up depth in the 50s and last-mile work near 60 are different decade jobs — not this page. Sizing the eventual nest egg (spending → gap → pot) is a separate method — use CRIC and MSCA for personal estimates; don’t rebuild a 25× waterfall here.
Where the money sits — RRSP, TFSA, FHSA if a first-home goal competes, workplace plan — is TFSA vs RRSP vs FHSA. This page doesn’t re-rank accounts. If home vs retirement competes, FHSA Rules is the one-clause pointer.
Public pensions are a future floor, not a reason to skip saving at 40. If you want stamps: CPP max at 65 is $1,507.65/mo (January 2026); average new at 65 is $877.01/mo (April 2026); OAS Jul–Sep 2026 maxima are $751.97 (65–74) and $827.17 (75+). Cite canada.ca — this isn’t a benefits tutorial.
Taylor’s vignette (Saskatoon)
The figures below are an illustrative sanity check — not advice, not a forecast, and not a fail grade.
Taylor is about 40 in Saskatoon, earns $80,000 gross, has no workplace DB in this illustration, and is juggling a mortgage and young kids. Invested retirement balance (RRSP + TFSA, illus.): $52,000 — above the ~$30,000 median band, well below the $240,000 3× guideline. Gap to the guideline: $188,000. Between median reality and the aspirational multiple is a normal place to sit.
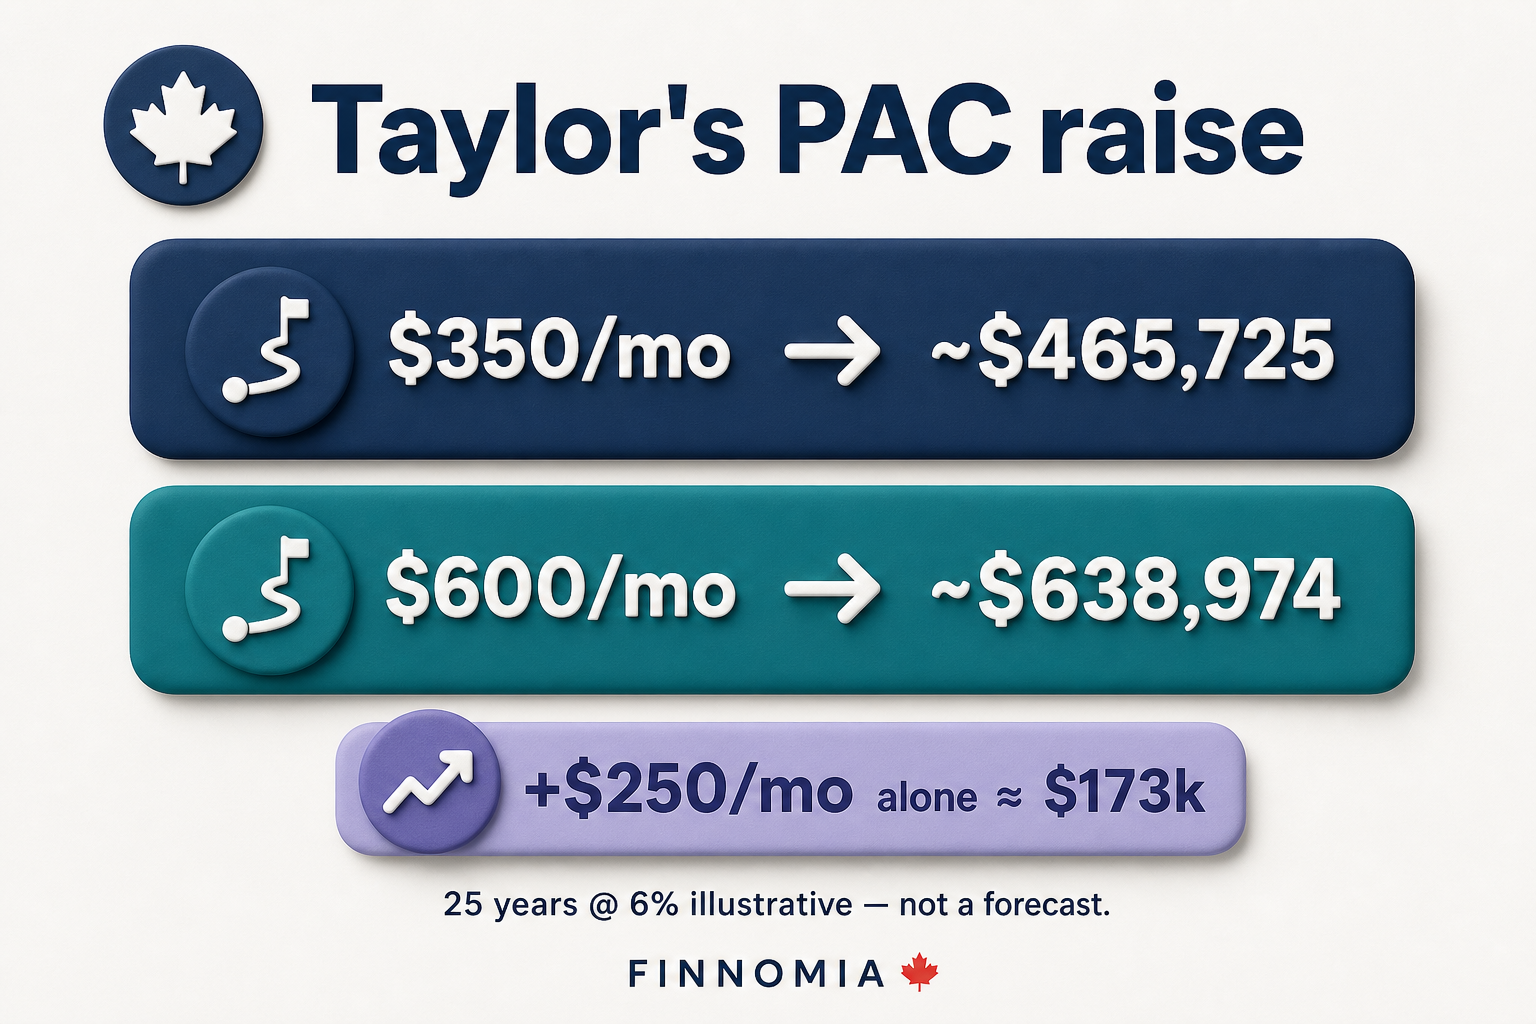
Habit / runway illustration. Assumptions: 25 years to about age 65; 6% annual return (illustrative constant — not a forecast); end-of-month contributions; returns reinvested; today’s dollars; no fee or tax drag modelled.
| Item | Amount |
|---|---|
| Current PAC | $350 / month |
| Raise | +$250 / month → $600 / month |
| Years | 25 |
| Illustrative return | 6% / year |
| Path | Future value (illus.) |
|---|---|
| $52,000 balance alone @ 6% / 25 yrs | ~$223,177 |
| Keep $350/mo PAC (annuity FV) | ~$242,548 |
| Total if keep $350 | ~$465,725 |
| Raise to $600/mo PAC (annuity FV) | ~$415,796 |
| Total if raise to $600 | ~$638,974 |
| FV of the +$250/mo alone | ~$173,248 |
Over 25 years, $350 × 12 × 25 = $105,000 contributed; $600 × 12 × 25 = $180,000; the extra $75,000 cash compounds to about $173,000 of terminal value in this illustration. At a 5% return, the raise alone is still roughly $149,000 — still material; label the assumption.
Whether Taylor’s cash flow can sustain +$250 a month is owned by How Much Should You Save Each Month? — this page doesn’t reteach surplus math. Once an amount exists, How to Automate Savings Goals in Canada is the PAC. Liquidity before optimizing retirement PACs is How Much Emergency Fund Do I Need in Canada?. Cash-flow hygiene: How to Budget in Canada.
Tools and next checks
Later: My Service Canada Account and the Canadian Retirement Income Calculator for multi-source estimates (estimates only). Now: Finnomia’s Retirement Planner via trial for age-checkpoint and scenario estimates — not advice.
See the checkpoint beside your other numbers
Finnomia’s Retirement Planner builds progress and scenario estimates — not advice. It tracks those scenarios; it doesn’t hold accounts or move money. If you want that sitting next to your other numbers, start a 14-day free trial.
How much should I have saved for retirement at 40 in Canada?
There’s no pass/fail CAD balance. A Fidelity-style ~3× salary checkpoint is a guideline, not law. Typical 35–44 median RRSP/RRIF/LIRA balances sit near ~$30,000 in widely cited SFS aggregations — far below 3× for many salaries.
Is 3× salary a Canadian rule?
No. It’s a Fidelity-style / US-rooted milestone often reused on Canadian sites. Use it as a goalpost, not a CRA or Service Canada grade.
What should I do if I’m behind the 3× number?
Lock or raise an automatic contribution while you still have ~20–25 years of runway. Check whether cash flow can sustain it on the monthly-save page; choose accounts on TFSA vs RRSP vs FHSA.
This article was published in September 2026 and is general information, not personalized tax, legal, or retirement advice. Guideline multiples and median aggregations are not personal targets. Confirm contribution room on CRA and your own estimates in My Service Canada Account / CRIC.