
On this page
- What counts as an asset?
- What counts as a liability?
- A household example
- Avoid the most common double counts
- Registered balances are not equally spendable
- Gross net worth versus after-tax planning value
- RESP balances and household net worth
- Pensions and LIRAs
- Home values without false precision
- Vehicles and personal property
- Joint and separate household assets
- Measuring progress without being misled by markets
- Net worth frequency and recordkeeping
- Complete-net-worth checklist
- Convert foreign holdings consistently
- Track the trend, not just today’s total
How to Track Your Complete Net Worth in Canadian Dollars
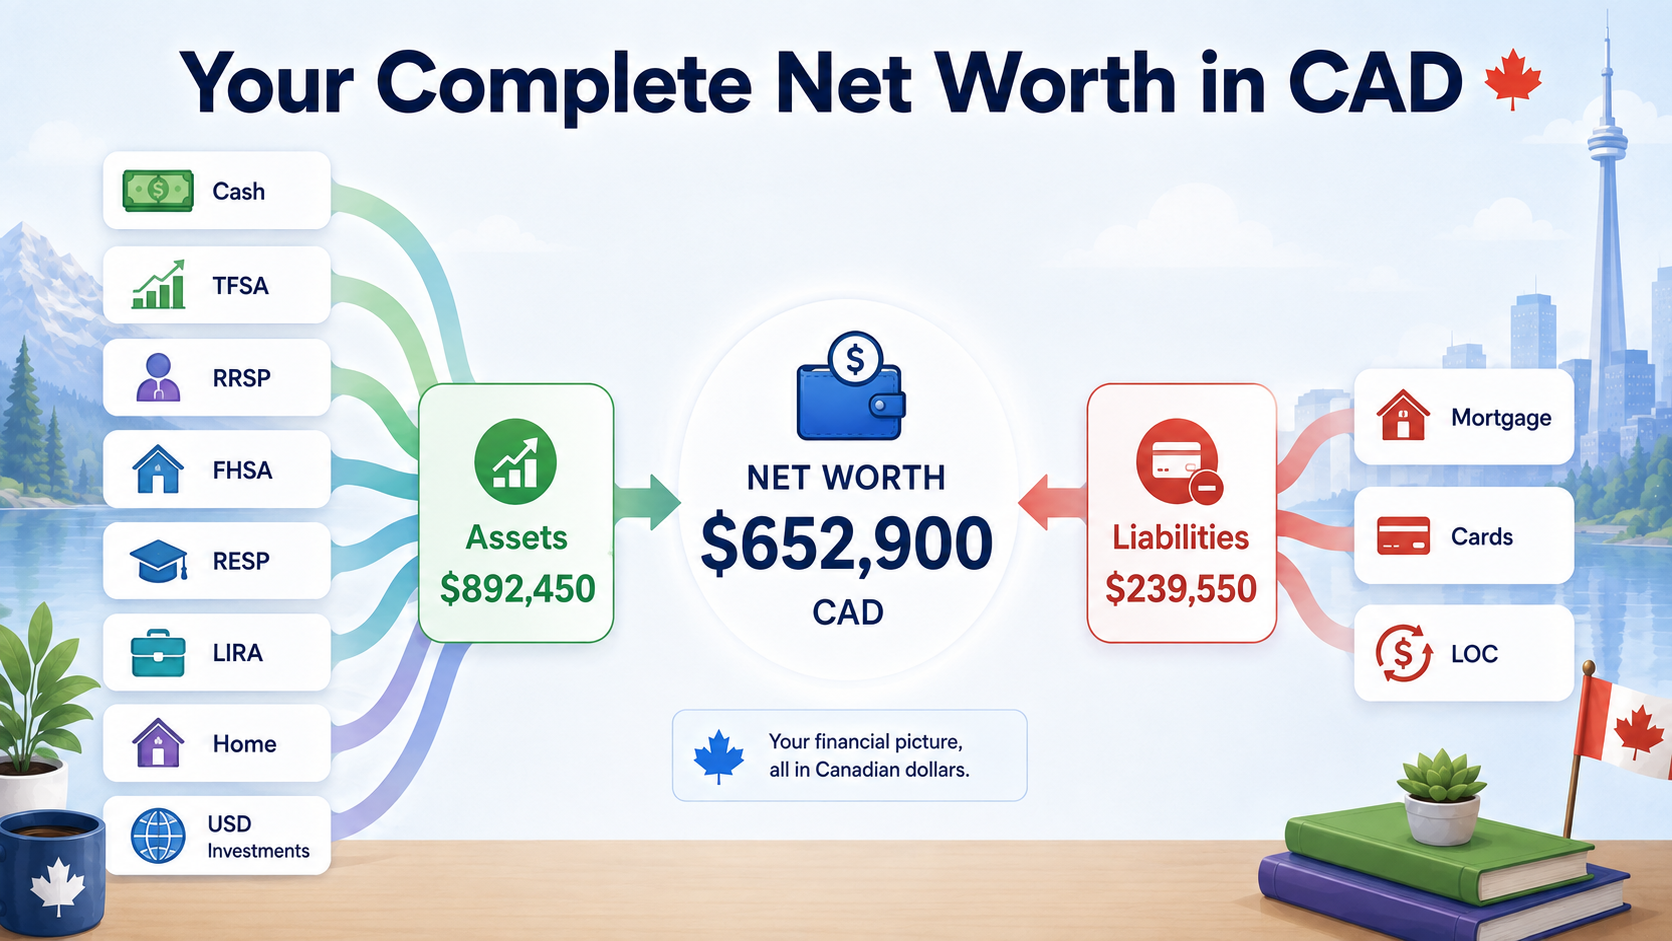
Your net worth is the value of what you own minus what you owe:
assets − liabilities = net worth
For a Canadian household, the useful view brings cash, property, investments and registered accounts—TFSA, RRSP, FHSA, RESP and LIRA—together in CAD, then subtracts mortgages, credit cards, lines of credit and loans.
What counts as an asset?
Include current balances or reasonable market values for:
- chequing and savings;
- TFSAs;
- RRSPs and RRIFs;
- FHSAs;
- RESPs;
- LIRAs and pensions with an available value;
- non-registered investments;
- real estate;
- business equity, where it can be valued reasonably; and
- material vehicles or other assets if including them helps decisions.
Registered accounts count at their current balance. Contribution room does not count. Room is permission to contribute, not an asset you own.
What counts as a liability?
Include current amounts owed:
- mortgage principal;
- credit-card balances;
- personal and home-equity lines of credit;
- student, auto and personal loans;
- taxes payable; and
- other enforceable debts.
Credit limits do not count. A $20,000 unused line of credit is borrowing capacity, not cash or an asset.
A household example
| Assets | Amount |
|---|---|
| Cash and savings | $28,000 |
| TFSAs | $83,000 |
| RRSPs | $150,000 |
| FHSA | $16,000 |
| RESP | $25,000 |
| Non-registered investments | $30,000 |
| Home | $650,000 |
| Total assets | $982,000 |
| Liabilities | Amount |
|---|---|
| Mortgage | $410,000 |
| Line of credit | $10,000 |
| Credit cards | $2,000 |
| Total liabilities | $422,000 |
Net worth = $982,000 − $422,000 = $560,000
Avoid the most common double counts
Transfers between your own accounts
Moving $5,000 from chequing to a TFSA changes the location of an asset, not total net worth. If you count both the old cash balance and new TFSA balance before the transfer settles, the total is temporarily inflated.
Investment accounts and their holdings
Count either the account’s total value or all holdings plus cash inside it—not both.
Credit-card purchases and payments
The card balance is the liability. A payment reduces chequing and the card by the same amount, so the transfer itself does not create a new expense or change net worth, apart from interest or fees.
Home value and mortgage
Include the full home value as an asset and the mortgage principal as a liability. Do not include “home equity” as an additional asset; that would count it twice.
Registered balances are not equally spendable
Two accounts with the same balance can have different tax and access consequences:
- TFSA withdrawals are generally tax-free.
- RRSP and LIRA withdrawals are generally taxable and may be restricted.
- FHSA withdrawals are tax-free only when qualifying conditions are met.
- RESP withdrawals involve contribution and education-assistance components with different treatment.
Net worth is a useful total, but it is not the same as liquid spending money. Track liquidity and account type beside the number.
Gross net worth versus after-tax planning value
Standard net worth uses current account balances and subtracts liabilities. It does not normally reduce an RRSP or LIRA by an estimated future tax bill.
That convention keeps the calculation objective and avoids pretending the future tax rate is known. For retirement planning, however, it can be useful to maintain a separate after-tax scenario. A $100,000 TFSA and a $100,000 RRSP both add $100,000 to standard net worth, but they do not create the same spendable retirement income.
Do not mix the two methods from month to month. Label any tax-adjusted scenario clearly.
RESP balances and household net worth
An RESP is an asset controlled by the subscriber, but part of the balance may include government grants and accumulated income intended for the beneficiary’s education. If conditions are not met, not every dollar will necessarily remain available to the household.
Including the current account value in net worth is a reasonable standard approach. Track the education purpose separately so the total is not mistaken for unrestricted retirement or emergency money.
Pensions and LIRAs
A LIRA with a current market value fits naturally as an investment asset. A defined-benefit pension may not provide an account balance that can be added directly.
Possible approaches include:
- exclude the pension from standard net worth and track projected retirement income separately;
- include an official commuted value when current and relevant; or
- maintain a separate expanded retirement balance sheet.
Avoid inventing a pension value from future monthly payments without a sound actuarial method.
Home values without false precision
Use a consistent, reasonable estimate from a recent appraisal, comparable sales, a municipal assessment adjusted for known limitations or a conservative market estimate. Updating it every day adds volatility without much decision value.
Quarterly or annual home-value updates are often enough. Record renovation spending as spending or capital improvement; do not automatically add every renovation dollar to home value.
Vehicles and personal property
Including a vehicle can improve completeness when it is valuable and has a loan. Use a realistic resale value, not replacement cost. Everyday furniture, electronics and clothing are usually excluded because resale values are low and difficult to maintain.
Consistency matters more than including every asset. If vehicles are included, update their values periodically and include the associated loans.
Joint and separate household assets
A household view can combine shared and individual accounts without changing legal ownership.
For joint accounts, count the balance once. For separate accounts, decide whether the view represents one person or the household. Do not include a partner’s full asset in one personal calculation and again in the household total without a clear scope.
Finnomia’s separate user accounts and household views are designed to preserve that distinction.
Measuring progress without being misled by markets
Net worth can fall during a month when you made good decisions because markets declined or CAD strengthened against USD holdings. It can rise during a month when spending was high because property or investments increased.
Separate the drivers:
| Driver | Example |
|---|---|
| Contributions | Cash added to investments |
| Debt reduction | Mortgage or loan principal repaid |
| Market movement | Security prices changed |
| FX movement | USD holdings changed in CAD value |
| Valuation update | Home or vehicle estimate changed |
This shows what the household controlled and what the market supplied.
Net worth frequency and recordkeeping
Monthly tracking is useful for active budgeting and debt payoff. Quarterly may be sufficient for a stable household. Use the same approximate date and valuation rules each period.
Keep historical snapshots. Correct true duplicates or missing accounts, but avoid rewriting old values every time an estimate changes. The trend is most useful when the method remains consistent.
Complete-net-worth checklist
- Define whether the scope is personal or household.
- Count each account and property once.
- Include current debt principal, not credit limits.
- Exclude contribution room.
- Convert foreign assets consistently.
- Track liquidity and account restrictions.
- Separate controlled progress from market and FX movement.
- Review beneficiaries, ownership and account labels periodically.
Convert foreign holdings consistently
If you hold USD cash or investments, choose one reporting currency and one consistent exchange-rate source. Finnomia reports CAD and USD using Bank of Canada FX data, allowing the total to be viewed coherently in Canadian dollars while preserving the original currency context.
Exchange-rate movements can change reported CAD net worth even when the USD asset price does not move.
Track the trend, not just today’s total
Update net worth monthly or quarterly. Look for the drivers:
- savings and investment contributions;
- debt principal reduction;
- market movement;
- property-value changes; and
- foreign-exchange movement.
Finnomia brings connected cash, debts, investment holdings and registered accounts into one net-worth view, with household finances supported through separate user accounts. Connections are read-only.
For the distinction between account balance and contribution room, see registered accounts and net worth in Canada. For annual room, use the contribution limits cheat sheet.